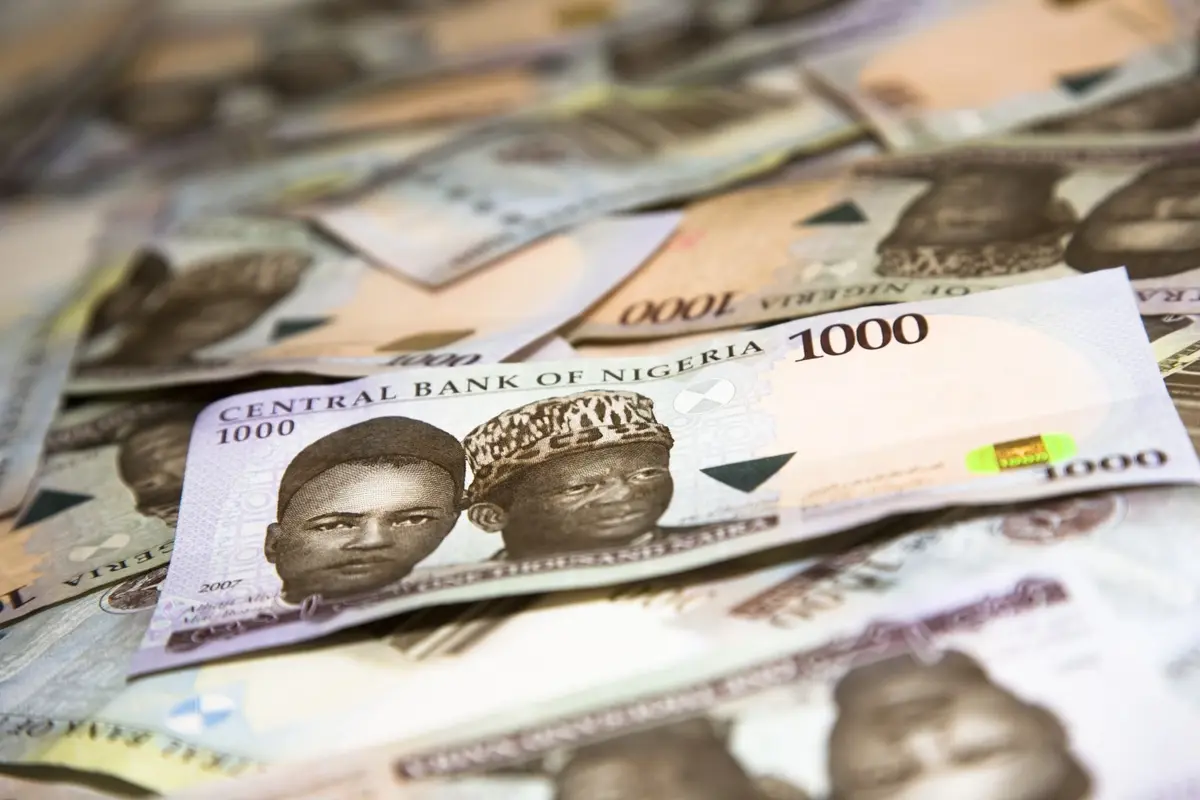
Nigeria's growing reliance on domestic borrowing is intensifying competition for bank credit, prompting concern that the government's ability to pay attractive yields on its securities could restrict the flow of affordable financing to businesses and households, even as banks emerge from a major recapitalisation exercise.
The pressure is mounting as the Federal Government continues to fund large fiscal deficits through the domestic market, with Nigerian banks among the principal buyers of government securities.
In its 2026 Article IV assessment, the International Monetary Fund (IMF) pointed to constraints on private-sector credit expansion, including banks' holdings of government securities and tight monetary conditions. The IMF estimated that Nigerian banks' holdings of government securities represented about 22 percent of total bank assets.
That raises a central question for the industry: whether the additional capital raised by banks will translate into significantly more lending to businesses, or whether a substantial share of expanded balance-sheet capacity will keep flowing into relatively attractive government securities.
Data show private-sector credit has been growing, albeit modestly. Credit to Nigeria's private sector rose to roughly ₦83.43 trillion in July 2026 from ₦81.04 trillion in May, an increase of ₦2.39 trillion over two months. The July figure nonetheless remained below the record high of ₦94.61 trillion recorded in February 2026.
The IMF projects continued expansion, forecasting private-sector credit growth of 14.2 percent in 2026. The concern is therefore not whether financial institutions are lending more, but whether government borrowing is absorbing a disproportionate share of the resources that could otherwise support private investment, particularly long-term lending to manufacturers, SMEs and infrastructure operators.
Professor Joseph Uwaleke, founding director of the Institute of Capital Market Studies, said bank recapitalisation was necessary to empower lenders to grow the economy and should enable them to invest raised capital in the most economically viable assets. He argued banks should direct their financial assets toward manufacturing and local production at lower interest rates. He added that revived companies will depend on financing from recently recapitalised local banks.